


Real estate company and researcher CBRE has approached a mix of 40 local and international banks and non-bank lenders for its ‘H2 Lenders Sentiment Survey’.
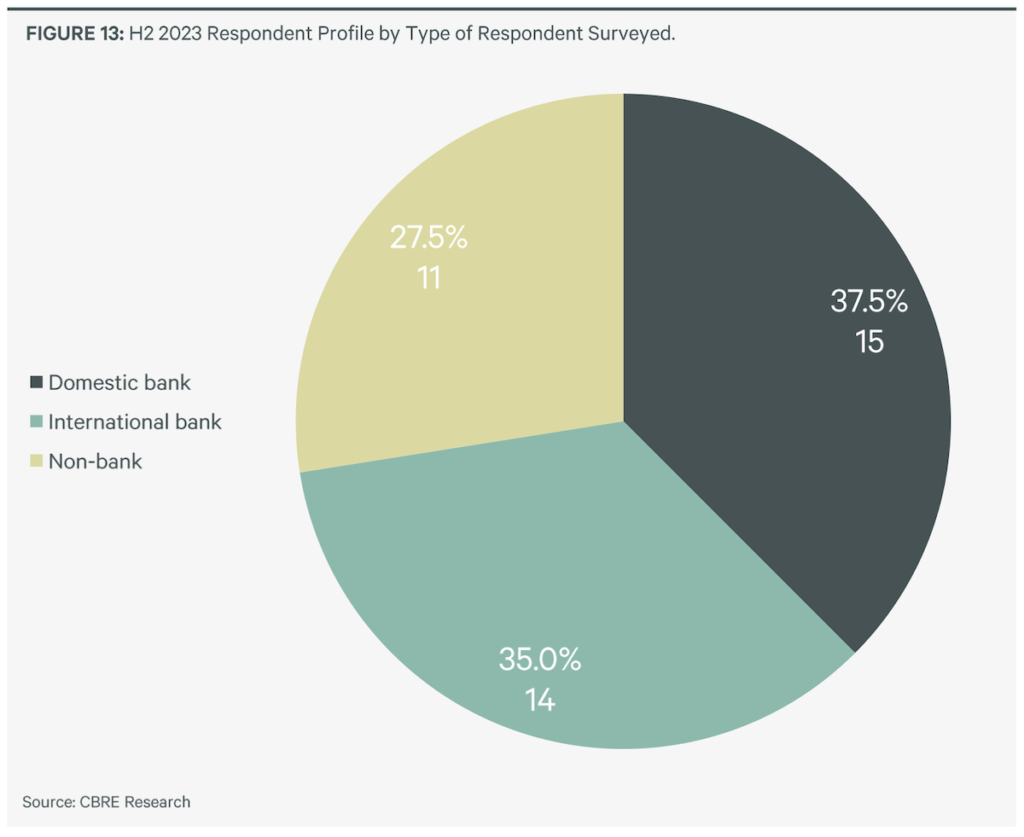
The CBRE Research H2 2023 Lenders Sentiment Survey was conducted over the end of October and beginning of November 2023. A total of 40 responses were received prior to the 7 November 2023 RBA Cash Rate Decision.
At a topline level, the results highlight a flattish appetite for new Australian property loans over the next three months, with 37% of respondents wanting to grow their loan book and 10% wanting to decrease.
“We anticipate this will start to play a role in office asset construction and re-development being pushed back or postponed indefinitely, except for well-capitalised landlords. For residential, nearly 60% of lenders expect over two thirds of the debt component of construction finance to be covered through pre-sales, which will continue to weigh on future supply.”
Will Edwards, Associate Director, Debt & Structured Finance, CBRE
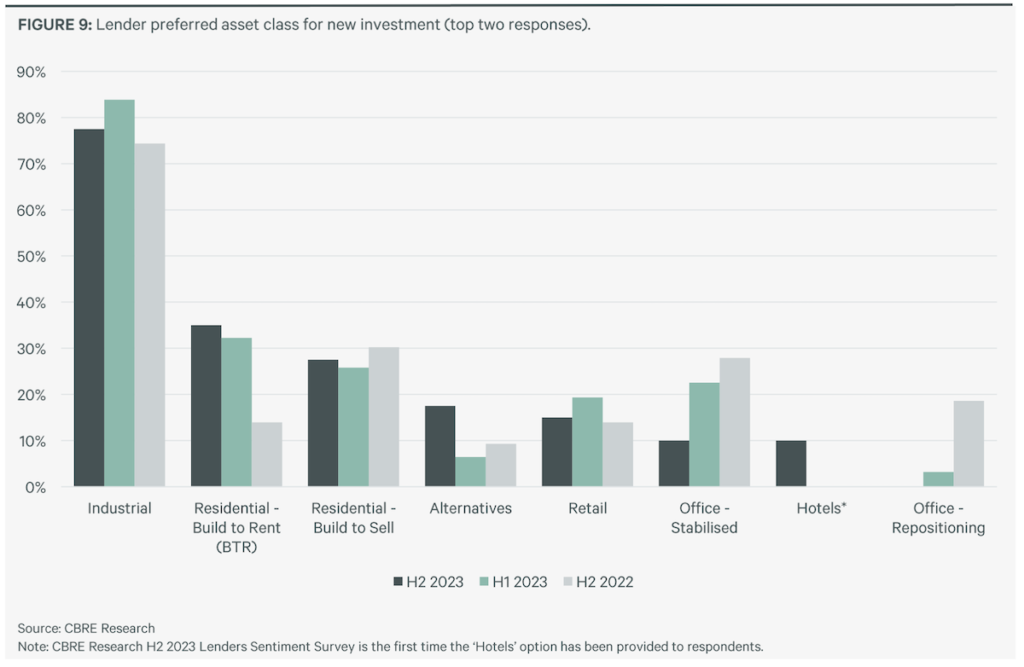
Financers have maintained their appetite for well-located, high-quality Build to Rent assets across Australia, with Build to Rent ranking second behind industrial on the list of preferred asset classes for new investment.
However, the most noticeable shift has been the appetite for investing in alternative assets such as data centres, health care, life sciences, childcare and self-storage, which has more than doubled since CBRE’s H1 2023 survey.
The survey also highlights that more offshore banks and non-bank lenders have grown their appetite for the Build to Rent asset class since CBRE’s last survey, with Mr Edwards noting that transactional evidence around both cap rates and rents was expected to propel sentiment towards the sector moving forward.


